Insurance in Setúbal, Complete Expat Guide 2026
Why Expat Insurance in Setúbal Is Different
Setúbal doesn't get the same attention as Lisbon or the Algarve, and that's exactly why expats who move here love it. It's a working Portuguese city, roughly 50 km south of Lisbon across the Sado river, with a real community feel, lower costs, and some of the most dramatic natural scenery in the country right on its doorstep. But that combination of factors also shapes your insurance picture in ways that differ from what you'd face in the capital.
The expat community in Setúbal is genuinely mixed. You'll find British retirees who've settled here for the affordability and the proximity to Lisbon without the Lisbon price tag, plus a growing number of French and Belgian households, some remote workers priced out of the capital, and a long-established Brazilian community. The total foreign resident population in Setúbal district has grown sharply in recent years, tracking the national trend, and you'll hear English and French in the cafés around Praça do Bocage more often than you might expect.
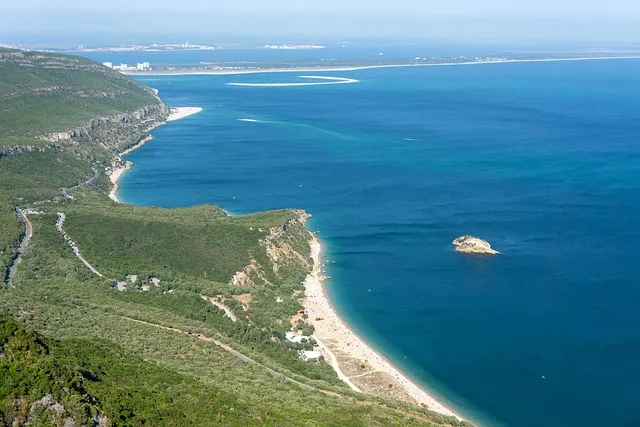
What makes expat insurance in Setúbal specifically interesting is the risk profile. The Serra da Arrábida creates wildfire exposure that's higher than in central Lisbon. The Sado estuary and low-lying areas near the waterfront carry flood risk after heavy rainfall. The EN252 and A2/A12 motorway junctions bring genuine traffic pressure for commuters, which influences car insurance premiums. And if you're renting in the older housing stock closer to the centre, you'll want to pay close attention to the structural cover clauses in your home policy.
Every insurance contract sold in Portugal is regulated by the ASF, Autoridade de Supervisão de Seguros e Fundos de Pensões. Only professionals registered with the ASF can legally sell you an insurance contract. Before you sign anything, you can verify a broker or insurer's registration at asf.com.pt. This applies whether you're buying from a local Setúbal office, a Lisbon broker, or an online platform.
Car Insurance in Setúbal
Car ownership is effectively non-negotiable for most expats in Setúbal. Public transport connects the city to Lisbon via ferry and the Fertagus suburban rail, which is genuinely useful if you work in the capital. But getting around Setúbal itself, reaching the Arrábida beaches, or making the school run to Palmela or the surrounding parishes requires a car. That means car insurance Portugal needs to be one of your first priorities when you arrive.
Third-party liability (RC Automóvel) is the legal minimum and it's mandatory for every vehicle registered or regularly driven in Portugal. You'll need this before you can register a foreign-plated car or transfer a UK/EU registration into the Portuguese system.
What Car Insurance Costs in Setúbal
Setúbal sits in a mid-range risk zone for car insurance pricing. It's cheaper than Lisbon or Porto, but pricier than rural Alentejo. Here's a realistic picture for 2026:
- Third-party only (RC): €350–550/year for a standard family car
- Third-party, fire and theft: €450–700/year
- Comprehensive (todos os riscos): €700–1,400/year, depending heavily on the car's value and your claims history
A few Setúbal-specific factors push premiums around. The A2 motorway junction at Setúbal and the EN10 coastal road toward Sesimbra see higher accident frequency, so if your registered address is close to those corridors, some insurers price slightly higher. Parking in the city centre is tight, and incidents in car parks and narrow streets are a common claims category. If you're keeping a motorcycle for the Arrábida roads in summer, look at motorcycle insurance Portugal separately, it's a distinct policy and the Arrábida's winding roads mean you'll want solid third-party cover at minimum.
Foreign-plated cars are a real issue that catches expats out. If you're a Portuguese tax resident and you drive a UK or non-Portuguese EU car, you generally have 183 days to re-register it in Portugal. After that, driving it is illegal and your insurance can be invalidated. Sort this early.
Health Insurance in Setúbal
The public health system in Setúbal is anchored by Hospital de Setúbal (São Bernardo), which provides emergency and inpatient care. Access to a local health centre (centro de saúde) is free once you register with the SNS, the Serviço Nacional de Saúde, but wait times for specialist consultations can stretch to months. For most expats, private health insurance Portugal expats is the practical solution for anything beyond emergency care.
Private Health Insurance Options for Setúbal Expats
Private healthcare in Setúbal itself is more limited than in Lisbon. The main private clinics are clustered in the city centre, and for more complex procedures or specialist care, most insured expats go to Lisbon, typically CUF, Luz Saúde, or similar hospital groups, which are well within reach. That's worth factoring into your policy choice: make sure your plan covers treatment in Lisbon private hospitals, not just Setúbal-area clinics.
Typical annual premiums for private health insurance in the Setúbal area in 2026:
- Age 30–40, basic plan: €600–900/year
- Age 45–55, mid-range plan: €900–1,400/year
- Age 60–70, comprehensive plan: €1,400–2,800/year
- Family of 4 (2 adults, 2 children): €2,200–4,000/year
British expats who arrived before 2021 and hold a valid S1 certificate from HMRC can access SNS cover under that arrangement, but you still need to register it correctly with the local health centre. Don't assume it's automatic. For dental care, your main health policy almost certainly won't cover it adequately. A standalone dental insurance Portugal plan typically costs €100–250/year and covers routine consultations, X-rays and a meaningful portion of treatments. Given that private dentist visits in Setúbal run €60–120 for a basic consultation, the maths usually works out.
Home and Property Insurance in Setúbal
Whether you're renting a flat near the waterfront, buying a house in Azeitão, or settling into a villa in the hills above Palmela, your approach to home insurance Portugal needs to reflect the specific risks of this part of Portugal.
Wildfire Risk
This is the factor most new arrivals underestimate. The Serra da Arrábida and the pine and eucalyptus-covered hills to the north and east of Setúbal have seen serious wildfire events. If your property has any rural or semi-rural exposure, read your policy's wildfire exclusions carefully. Standard multirisk home policies in Portugal do typically include fire, but some have specific exclusions or sub-limits for properties classified as being in high-risk forest zones. Ask your broker directly: "Does this policy cover wildfire damage to the structure and contents?" Get the answer in writing.
Flood and Damp
Lower-lying areas near the Sado estuary and some older streets in the city centre can flood after sustained winter rain. More common is penetrating damp in older apartment buildings, this is often a building (condomínio) insurance issue rather than your individual policy, but the boundary between the two can get contentious after a claim. If you're buying rather than renting, check what the condomínio's policy covers before assuming you're protected.
What Home Insurance Costs in Setúbal
- Rented apartment, contents only: €80–160/year
- Owned apartment, multirisk (building + contents): €180–350/year
- Owned house with land, comprehensive cover: €300–600/year depending on rebuild value
If you have a mortgage, your bank will require a building insurance policy, that's non-negotiable. You're legally entitled to use your own insurer rather than the bank's tied product, though you'll sometimes need to push back on this. An independent broker can almost always find you better terms than the bank's default offering.
Renters' Rights and Contents Cover
If you're renting, your landlord's policy covers the building, not your possessions. A contents policy is your own responsibility and it's genuinely worth having, even for short-term rentals. Contents cover for a standard 2-3 bedroom apartment in Setúbal typically runs €80–140/year and covers theft, fire, and accidental damage to your belongings. If you work from home and have expensive equipment, declare it specifically, many standard contents policies cap electronics cover at €500–1,500 unless you specify higher limits.
Life Insurance for Expats in Setúbal
Life insurance becomes particularly relevant in two situations: you've bought a property with a mortgage (Portuguese banks require decreasing term life insurance linked to the loan), or you have dependants relying on your income. For expats in Setúbal, the cost of living context matters here. A family home in the Setúbal district, whether in the city itself, in Azeitão, or in Palmela, costs significantly less than the equivalent in Lisbon or the Algarve coast, which means your mortgage cover requirement may be lower. But your income replacement needs are real regardless.
Standard term life insurance Portugal expat policies for a 40-year-old non-smoker typically run €15–35/month for €150,000–200,000 of cover. If your mortgage is smaller, your obligatory bank-linked policy may cost less. The key watch-out for expats: some Portuguese life policies have residency requirements or exclusions related to repatriation. Make sure the policy pays out to your beneficiaries in your home country without complications.
Critical illness cover (doenças graves) is often worth adding, it's a separate or riders product that pays a lump sum on diagnosis of specific conditions rather than death. Premiums vary significantly by age and health history.
Professional and Freelance Insurance in Setúbal
Setúbal attracts a quiet but growing number of remote workers and freelancers, people who want a genuine Portuguese city experience at lower costs than Lisbon, with good road and rail connections when they need the capital. If you're working as a freelancer, independent contractor, or running a small business registered in Portugal, you need to think about professional liability.
In Portugal, professional liability insurance is known as Responsabilidade Civil Profissional (RC Profissional). For some professions, architects, lawyers, accountants, healthcare professionals, it's legally mandatory. For consultants, designers, developers, and other knowledge workers, it's not always required by law but it's strongly advisable if you're delivering work to clients. A single disputed project can expose you to claims that exceed your annual income.
If you're invoicing as a trabalhador independente (self-employed under NIF), you may also need to check your tax category and whether your activity class has specific regulatory requirements. A comprehensive guide to professional liability insurance Portugal covers this in more detail, but the short version is: if you're billing clients for professional services, get RC Pro. Annual premiums for standard freelance professional liability policies start at €250–450/year for €50,000–100,000 of cover.
For expats who travel regularly for work or take extended trips back to the UK, France, or Belgium, travel insurance Portugal is worth reviewing too. If you already have comprehensive private health insurance with international cover, check whether it includes emergency repatriation and trip cancellation, many do, which means you may not need a separate travel policy for short EU trips.
The Expat Community in Setúbal, What Locals Know
Setúbal is genuinely different from the Algarve expat experience. You won't find English-language estate agents on every corner or expat-only golf clubs. What you will find is a community of people who chose Portugal for real reasons, lower costs, authentic culture, access to nature, and who tend to integrate more deeply into Portuguese daily life as a result.
Where Expats Tend to Settle
British and French retirees often settle in the quieter parishes outside the city: Azeitão (famous for its moscatel wine and manor houses), Palmela (hilltop castle town with excellent views), and the coastal strip toward Sesimbra. Families with children often look at these areas for the combination of good schools, outdoor space, and manageable cost of living. Younger remote workers tend to stay closer to the city centre for the café culture, the ferry connection to Lisbon, and the social scene around Praça do Bocage.
Cost of Living Context
This matters for insurance because your asset values, your income, and your risk profile all feed into what cover you actually need. A 2-bedroom flat in central Setúbal rents for €800–1,100/month, roughly 30–40% less than the Lisbon equivalent. Property purchase prices in the Setúbal district run €1,500–2,500/m² for standard residential stock, rising toward €2,800–3,500/m² for premium properties in Azeitão or seafront locations. These figures directly affect how much building cover you need and what your mortgage-linked life policy should look like.
Portuguese Language and Insurance
Here's the practical reality: most insurance documentation in Setúbal will be in Portuguese, and most local insurance agents operate in Portuguese. Unlike the Algarve where English-language services are common, Setúbal has fewer expat-focused brokers. This makes working with an English or French-speaking broker, even one based in Lisbon, genuinely valuable. You need to understand what you're signing, and a policy clause you misread because of a translation gap can create serious problems at claim time.
The Wildfire Season Reality
Every long-term Setúbal resident will tell you the same thing: summer wildfire risk is real, and the alerts in July–September are taken seriously. Local knowledge says you should review your home insurance policy before June each year, check that your wildfire cover is active and not subject to seasonal exclusions, and make sure your insurer has your current phone number for emergency notifications. This isn't paranoia, it's what sensible residents do.
How to Get Insured in Setúbal: Step by Step
- Get your NIF (número de identificação fiscal). You can't take out a Portuguese insurance contract without one. Visit your local Finanças office or do it via a solicitor if you're not yet in Portugal.
- Get your NHR or residency certificate (if applicable). Your residency status affects which SNS health services you can access and whether certain insurers will quote you without restrictions.
- List what you need to insure. Car, health, home (building and/or contents), life, professional liability, write it down before you speak to anyone. Being clear about what you need stops you being upsold things you don't.
- Work with an ASF-licensed broker. Only professionals registered with the ASF (asf.com.pt) can legally sell insurance contracts in Portugal. An independent broker can access multiple insurers and find you better terms than going direct. Request their ASF registration number before you proceed.
- Provide accurate information. For health insurance, declare pre-existing conditions honestly. For home insurance, give the correct rebuild value, not the market price. Underinsurance is a common and costly mistake.
- Read the policy summary (Informação Pré-Contratual) before signing. You're legally entitled to this document in Portuguese. If you need it explained, ask your broker to walk through the key exclusions with you.
- Keep digital copies of everything. Policy documents, premium receipts, emergency contact numbers for your insurer. Store them somewhere you can access if your home is damaged or you're hospitalised.
- Review annually. Your circumstances change, new car, renovation, salary increase, new family member. Your insurance should reflect that. Set a calendar reminder each year before renewal.
Ready to Sort Your Insurance in Setúbal?
Tell us what you need, and we'll connect you with an ASF-licensed broker who covers the Setúbal area and speaks your language. No obligation, no sales pressure.
Get Your Free Quote, Takes 2 MinutesFrequently Asked Questions
Do I need different insurance in Setúbal versus Lisbon?
Your mandatory insurance requirements are identical across Portugal, third-party car insurance is the law wherever you live, and the same rules apply. What differs is the risk context and sometimes the pricing. In Setúbal, wildfire and flood risk are more relevant for home insurance than in central Lisbon. Car insurance premiums in Setúbal are typically 10–20% lower than in the capital because traffic density and theft rates are lower. Private health insurance quotes won't differ meaningfully by city, but you'll want to confirm that your chosen plan covers private treatment at Lisbon hospitals, since Setúbal's private healthcare network is more limited.
How does living near the Arrábida Natural Park affect my home insurance?
Properties within or directly adjacent to the Arrábida Natural Park fall into a higher wildfire risk zone. Some insurers apply sub-limits or specific exclusions to properties in classified high-risk forest areas. Before you finalise a home purchase in the hills above Setúbal or in rural Azeitão, ask your broker to confirm wildfire cover explicitly. A standard multirisk policy from a reputable insurer should include it, but the terms vary and some cheaper policies exclude or cap it. Getting written confirmation of wildfire cover before you sign anything is essential.
Can I use my European Health Insurance Card (EHIC) or GHIC in Setúbal?
UK residents visiting Portugal can use the Global Health Insurance Card (GHIC) for access to SNS emergency treatment at the same cost as Portuguese nationals. But if you're a Portuguese tax resident, you're no longer a UK visitor, you're a resident, and the GHIC doesn't apply to you in your country of residence. Once you're resident in Portugal, you need to either register with the SNS using your S1 certificate (if you have one from HMRC) or take out private health insurance. EU citizens resident in Portugal access the SNS through standard residency registration and social security contributions.
What health insurance do digital nomads and remote workers use in Setúbal?
Most remote workers on the Portugal Digital Nomad Visa (D8) or those working as freelancers choose international private health insurance that covers both Portugal and their home country, or broader EU/worldwide cover. Plans from international providers often work well for this. Costs typically run €600–1,100/year for a 28–40 year old with a mid-range international plan. If you're registered as a permanent resident rather than on a temporary visa, a Portuguese domestic private health insurance plan is usually better value and gives you access to the same private hospital networks.
Is flood insurance included in standard home policies in Setúbal?
It depends on the policy and the property. Most standard Portuguese multirisk home insurance policies include "water damage" cover, but the definition varies. Cover for flooding from external sources (rising river or estuary water) is often separate from plumbing and internal water damage. For properties in lower-lying areas near the Sado estuary, ask your broker to confirm that external flood risk is explicitly covered. Some insurers offer this as standard; others require it as an add-on at an additional premium. Properties in designated flood plains may also face higher premiums or specific exclusions.
How does the commute to Lisbon affect my car insurance?
If you commute regularly to Lisbon, via the A2/Fertagus, or driving, you should declare your annual mileage and usage type accurately when getting a car insurance quote. Regular long-distance commuting typically pushes annual mileage above the thresholds for lower-risk categories, which can affect your premium. Some policies have different rates for "personal use only" versus "commuting use." Declaring inaccurate usage is a common mistake that can invalidate a claim. The Fertagus train is a genuine option for Lisbon commuters from Setúbal, and if you switch to train-based commuting and reduce your driving, you can declare a lower annual mileage at renewal.
Do I need professional liability insurance if I'm working remotely for a foreign company while living in Setúbal?
If you're a formal employee of a foreign company and you're not issuing invoices as a self-employed person in Portugal, your employer's liability cover may extend to you. But this needs to be confirmed with your employer explicitly, don't assume. If you're freelancing or invoicing clients directly as a Portuguese self-employed person (trabalhador independente), then yes, professional liability insurance is strongly advisable. For certain regulated professions, it's mandatory under Portuguese law regardless of where your clients are based. An ASF-licensed broker familiar with expat and remote work situations can clarify exactly what you need based on your specific contract and activity type.
How do I find an English-speaking insurance broker in Setúbal?
Setúbal has fewer English-language insurance services than the Algarve or central Lisbon. Your best options are either to work with a Lisbon-based English-speaking broker who operates across Portugal (common, and effective, most correspondence and policy management is done remotely anyway), or to use a platform like Portugal Insurance Hub that connects you directly with ASF-licensed brokers experienced with expat clients. In-person meetings can always be arranged for complex cases, but day-to-day policy management, renewals and claims support are handled by phone, email and video call for most expats regardless of location.
Not sure which policies you actually need? Our free checklist walks you through every category, takes five minutes and saves