Insurance in Porto, Complete Expat Guide 2026
Why Insurance in Porto Is Different for Expats
Porto isn't Lisbon. That sounds obvious, but it matters enormously when you're sorting out your insurance. The city has its own risk profile, its own housing stock, and its own expat community, and insurers know it.
Porto is Portugal's second-largest city, home to around 230,000 residents in the municipality proper, with the greater metropolitan area pushing close to 1.7 million. The expat population has grown sharply since 2018, driven by tech companies relocating, digital nomads discovering the city, and a wave of British, French, American, and Brazilian residents drawn by comparatively lower rents than Lisbon and an authenticity that's harder to find in the capital.
That growth has had practical consequences for insurance. Rental prices in neighbourhoods like Bonfim, Cedofeita, and Foz do Douro have risen significantly, which means the contents of your home are worth more, and so is making sure they're properly covered. Property values in the historic Ribeira district have climbed steeply, making underinsurance a genuine risk for homeowners who haven't reviewed their policies recently.
The local insurance market is regulated by the ASF, the Autoridade de Supervisão de Seguros e Fundos de Pensões, which oversees all insurers and brokers operating in Portugal. Any professional who sells you an insurance contract must be registered with the ASF. You can verify a broker's registration at asf.com.pt. This matters because Porto has attracted some unlicensed intermediaries targeting expats, particularly in online expat Facebook groups.
Porto also has specific environmental risks that shape your premiums. The Douro river floods. The hills above the city create microclimates that concentrate rainfall. The narrow granite cobblestone streets of the Baixa are genuinely treacherous for drivers and cyclists alike. And while Porto is far less wildfire-prone than the Algarve or central Portugal, the pine and eucalyptus forest fringe to the north and east of the city, particularly toward Gondomar and Valongo, carries real fire risk in dry summers.
Understanding these local factors is the first step to making sure your insurance actually covers what it needs to.
Car Insurance in Porto, Requirements, Risks, and Real Costs
Car insurance is mandatory in Portugal. Every vehicle must carry at minimum seguro de responsabilidade civil, third-party liability insurance, or you cannot legally drive. This applies from the moment you register your vehicle in Portugal, which expats are generally required to do within six months of establishing residency.
Porto's driving environment is demanding. The city sits on steep hills, its historic streets are narrow and frequently one-way, and traffic density in the centre rivals Lisbon for sheer frustration. Parking is genuinely difficult in Bonfim, Baixa, and the area around Boavista, which pushes many residents toward underground car parks, increasing the risk of minor scrapes and bumps that don't make it onto insurance claims but do affect your no-claims history if they do.
Flooding is a real concern for car owners along the Douro waterfront and in low-lying parts of Gaia across the river. The October-to-March rainy season can produce flash floods that damage parked vehicles, a risk that basic third-party insurance does not cover. If you park regularly near the riverfront or in underground car parks in flood-prone areas, comprehensive insurance (seguro multirriscos automóvel) is worth serious consideration.
For motorbikes and scooters, increasingly common in Porto as residents try to navigate parking chaos, coverage requirements are identical to cars. You can find more detail on our full guide to motorcycle insurance Portugal.
What does car insurance actually cost in Porto? Rough ranges for 2026:
- Third-party only (seguro obrigatório): €350–€550/year for a standard mid-range car with a clean licence
- Third-party, fire and theft: €450–€750/year
- Comprehensive (multirriscos): €700–€1,400/year, depending on vehicle value, your age, and your claims history
Expats without a Portuguese driving history often pay 10–20% more initially, even with a clean foreign licence, because insurers have no local claims record to reference. Building up two to three years of clean Portuguese history brings premiums down noticeably. Our complete guide to car insurance Portugal covers the full requirements for transferring a foreign licence and registering a non-Portuguese vehicle.
One practical tip specific to Porto: if you live in the historic centre and use your car infrequently, tell your insurer. Some policies offer reduced premiums for low annual mileage, genuinely achievable if you're walking to the Mercado do Bom Sucesso and using the metro for most journeys.
Health Insurance in Porto, Private Coverage for Expats
Portugal has a national health service, the SNS (Serviço Nacional de Saúde), which expats with legal residency can access. In Porto, the main public hospitals are Hospital de São João and Centro Hospitalar Universitário de Santo António, both are competent, modern facilities. But wait times for non-emergency appointments are long, English-language availability is inconsistent outside specialist departments, and access to certain specialists can mean waits of several months.
This is why the majority of settled expats in Porto carry private health insurance, even those who also use the SNS for routine care. Private health insurance buys you shorter waiting times, English-speaking GPs, and access to Porto's well-developed private hospital network, which includes units like Hospital da Luz Porto and Hospital CUF Porto, both of which have dedicated expat and English-speaking services.
What does private health insurance cost in Porto in 2026?
- Ages 30–40, basic outpatient plan: €600–€900/year
- Ages 40–55, mid-range plan with hospitalisation: €900–€1,400/year
- Ages 55–65, comprehensive plan: €1,400–€2,200/year
- Ages 65+: €2,200–€3,800/year, with some variation based on pre-existing conditions
For digital nomads in Porto, a significant and growing community in the Boavista and Cedofeita areas, international health insurance policies designed for remote workers often provide better value than standard Portuguese private health policies, particularly if you travel frequently. These plans typically cost €800–€1,500/year for a healthy adult under 45 and cover you across multiple countries.
Dental coverage is generally excluded from standard health insurance plans. Porto has excellent private dental clinics, and costs without coverage can add up quickly: a basic check-up runs €40–€70, a filling €80–€150, an implant €1,200–€2,000. Standalone dental plans cost €150–€350/year and are worth adding to your health insurance stack. See our guide to dental insurance Portugal for a full breakdown.
For full details on plan types, pre-existing condition clauses, and what to look for in Portuguese private health policies, our guide to health insurance Portugal expats covers everything you need.
Home and Property Insurance in Porto, What You Actually Need
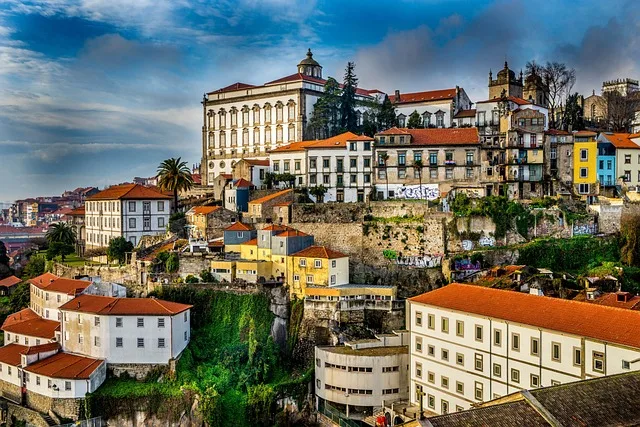
Porto's housing stock is one of the city's most distinctive features, and one of its biggest insurance challenges. Thousands of expats live in beautifully restored casas antigas (old townhouses) in Bonfim, Cedofeita, and Miragaia, many of which are well over 100 years old. These properties come with character, but also with specific risks: ageing plumbing, older electrical wiring, wooden floors and beams that are more vulnerable to fire and water damage, and a historic fabric that can be expensive to repair or replace.
Whether you're renting or buying, you need to understand what's covered and what's not.
Renters in Porto
If you're renting, your landlord's building insurance (seguro do edifício) covers the structure. It does not cover your personal belongings, your laptop, furniture, bicycle, or the contents of your wardrobe. You need a separate seguro de recheio (contents insurance) for that.
Contents insurance in Porto costs €150–€300/year for a typical two-bedroom apartment, depending on the declared value of your possessions. If you're working from home and have expensive equipment, multiple monitors, a high-end laptop, camera gear, make sure you declare it accurately. Many standard policies have per-item limits of €500–€1,000 that won't cover a €2,500 MacBook Pro without a specific rider.
Property Owners in Porto
If you own property in Porto, you need both building insurance and contents insurance. Lenders require building insurance as a condition of a mortgage, but even if you own outright, it's not optional in any practical sense.
Key risks specific to Porto that you want confirmed as covered:
- Water damage and flooding: Properties near the Douro riverfront, and basements or ground-floor units anywhere in the city, face real flood exposure. Check whether your policy covers inundação (flooding) explicitly, and what the conditions are, some policies cover burst pipes but not rising groundwater or river overflow.
- Structural damage in historic buildings: If you're buying a renovated townhouse, confirm your insurer understands the building's construction type. Granite-and-wood construction costs significantly more to repair than modern concrete builds.
- Subsidence: Porto's hillside topography creates some localised subsidence risk, particularly in areas that have seen rapid redevelopment.
Building insurance for an average Porto apartment runs €200–€500/year. A detached property or large townhouse can run €400–€900/year. Our full guide to home insurance Portugal explains multi-risk home policies and what to check before signing.
Short-term rental note: If you're letting your Porto property on Airbnb or similar platforms even occasionally, a standard home insurance policy almost certainly does not cover you during guest stays. You need a specific alojamento local (AL) rider or a dedicated short-term rental policy. This is not a grey area, claims during undisclosed rental periods are routinely rejected.
Life Insurance for Expats in Porto
Life insurance is less front-of-mind for many expats than health or home coverage, but for two groups it's genuinely critical.
First, if you have a mortgage in Portugal. Portuguese lenders typically require seguro de vida (life insurance) as a mandatory condition of a home loan, the policy must cover at minimum the outstanding mortgage balance. You can either take the bank's own policy (which is convenient but often overpriced) or arrange independent cover through a broker. Independent policies for the same coverage can cost 20–40% less than bank-bundled life insurance.
Second, if you have dependents, children, a non-working spouse, or family members who rely on your income. Porto's cost of living, while lower than Lisbon, has risen meaningfully: a two-bedroom apartment in Bonfim or Paranhos now rents for €1,200–€1,800/month. Losing the household's primary income without life cover would be genuinely devastating.
Term life insurance costs in Porto for 2026:
- Age 35, non-smoker, €200,000 cover over 20 years: €20–€40/month
- Age 45, non-smoker, €200,000 cover over 15 years: €40–€75/month
- Age 55, non-smoker, €150,000 cover over 10 years: €70–€140/month
Expats should be aware that some Portuguese life policies include exclusions for pre-existing conditions or require medical underwriting above certain coverage thresholds. Our guide to life insurance Portugal expat walks you through the underwriting process and what to declare.
Professional and Freelance Insurance in Porto
Porto has developed a genuine tech and creative economy over the past decade. Web Summit's long-running presence put the city on the global tech map, and the cluster of startups, agencies, and remote workers that followed has created a substantial community of self-employed expats who need professional insurance.
If you work as a freelancer, consultant, designer, developer, or any other independent professional in Porto, whether for Portuguese clients or international ones, you need to consider seguro de responsabilidade civil profissional, known in English as professional indemnity or professional liability insurance.
This coverage protects you if a client claims your work caused them financial loss. For tech professionals working on software projects, a coding error that causes a client's system to fail could result in a claim worth tens of thousands of euros. For designers or marketing consultants, copyright infringement claims or missed deadlines with contractual penalties can quickly exceed what any individual freelancer can absorb.
Professional liability insurance in Porto typically costs:
- Freelance tech/developer, €100,000 coverage: €300–€600/year
- Marketing/creative consultant, €100,000 coverage: €250–€500/year
- Architect or engineer (regulated professions): €600–€1,500/year, often mandatory through their professional association (Ordem)
Digital nomads on a D8 visa who are working remotely for non-Portuguese clients should also check whether their employer's liability policy follows them to Portugal, or whether they need independent cover. Many don't. Our full guide to professional liability insurance Portugal covers this scenario in detail.
One additional coverage worth mentioning for frequent travellers based in Porto: travel insurance. Even with solid health insurance, a standalone travel policy adds cancellation protection, baggage cover, and emergency repatriation benefits that most health policies exclude. If you're travelling regularly for work or leisure, easy to do given Porto's excellent international connections from Francisco Sá Carneiro Airport, our guide to travel insurance Portugal explains your options.
The Expat Community in Porto, What Long-Term Residents Know
Porto's expat community is large, well-connected, and genuinely useful when you're navigating the insurance market. Understanding who's here and what they've learned helps you avoid common mistakes.
The city's international residents skew younger than in the Algarve or Silver Coast. You'll find large communities of British, French, American, Brazilian, and Dutch expats concentrated in particular neighbourhoods. Bonfim has become notably popular with creative professionals and remote workers from northern Europe and North America. Foz do Douro attracts wealthier retirees and established business owners. Matosinhos, just north of the city proper, has a strong Brazilian and French expat presence drawn by its seafront and lower rents relative to central Porto.
What do long-term expat residents consistently flag about insurance in Porto?
Language remains a barrier. While many Porto professionals speak English, insurance documentation is almost universally in Portuguese. Policy terms, exclusion clauses, and claims procedures are written in legal Portuguese that's genuinely difficult to parse even with translation tools. Working with an ASF-licensed broker who speaks English isn't a luxury, it's the difference between understanding what you've bought and discovering a critical exclusion at claim time.
Don't underinsure your home contents. Expats who moved to Porto three or four years ago and set their contents policy at what their belongings were worth then are now significantly underinsured. Porto's property market has driven up the replacement cost of furniture and fittings, and remote workers have added high-value equipment. Review your declared value annually.
The informal advice in expat Facebook groups is often wrong. Porto has several active expat groups on social media with thousands of members, and insurance questions get plenty of answers, many of them inaccurate, out of date, or from people whose situation differs materially from yours. Use these communities for neighbourhood tips and restaurant recommendations. For insurance decisions, use an ASF-licensed professional.
Bundling policies saves money but requires care. Some Porto-based expats bundle home, life, and car insurance with a single insurer for a multi-policy discount. This can save 10–15% annually. Just make sure bundling doesn't lock you into a weak policy in one category for the sake of convenience in another.
How to Get Insured in Porto: Step-by-Step
If you've just arrived in Porto or you're reviewing inadequate coverage, here's a practical sequence that works.
- Sort your NIF first. Your Número de Identificação Fiscal (Portuguese tax number) is required for almost every financial transaction in Portugal, including insurance contracts. Get this from a local Finanças office, there's one in Porto Bonfim and one near the city centre, or through a lawyer. It usually takes a few days.
- Establish your residency status. Your insurance options and some policy conditions differ depending on whether you're on a tourist visa, a D7 passive income visa, a D8 digital nomad visa, or a full resident card. Be clear about this before applying for any policy.
- Prioritise car insurance if you have a vehicle. This is the only mandatory personal insurance in Portugal. You cannot wait on this one.
- Assess your health insurance needs. If you're employed by a Portuguese company, check what your employer provides. If you're self-employed, retired, or employed by a foreign company, you almost certainly need private cover.
- Review home risks for your specific property and neighbourhood. A ground-floor apartment near the Douro in Ribeira has very different insurance needs to a modern flat in Paranhos.
- Work with an ASF-registered broker. A licensed broker has access to multiple insurers, can compare policies properly, and is legally accountable for the advice they give you. This is especially important for expats navigating a system in a second language.
- Read, or have someone read, your policy document before signing. The exclusions section is where claims die. Know what's not covered before you need it to be.
Get Your Free Quote, Takes 2 Minutes
We'll connect you with an ASF-licensed English-speaking broker who works with expats in Porto every day. No obligation, no sales pressure, just clear, qualified advice tailored to your situation.
Get Your Free Quote, Takes 2 MinutesFrequently Asked Questions
Do I need different insurance in Porto compared to Lisbon?
Yes, in practical terms. Porto's specific risks, older building stock in the historic centre, Douro river flooding potential, steep cobblestone streets, and a high density of narrow urban roads, create a different risk profile than Lisbon. Home insurance should explicitly address flood and water damage if you're near the waterfront. Car insurance premiums in Porto can differ from Lisbon due to local accident and theft statistics. The regulatory framework (ASF) and mandatory requirements are identical across Portugal, but your policy content needs to reflect Porto's local conditions.
How does living in Porto affect my car insurance premium?
Porto's urban density, narrow historic streets, and heavy traffic in the centre mean insurers rate the city as moderate-to-high risk for minor collisions and scrapes. Premiums are generally comparable to Lisbon, though slightly lower on average. Where you park matters significantly: street parking in Bonfim or Baixa carries more risk than a secured garage in Matosinhos. If you have a garage or secured parking space, tell your insurer, it typically reduces your premium. Expats without a Portuguese claims history may pay 10–20% more initially regardless of a clean foreign record.
What health insurance do digital nomads use in Porto?
Porto has a large and active digital nomad community, particularly around Boavista, Cedofeita, and in co-working spaces like Second Home and Porto i/o. Most digital nomads here use one of two approaches: an international health insurance policy designed for location-independent workers (brands like Cigna Global, Allianz Care, or SafetyWing are common in expat conversations), or a standard Portuguese private health policy if they're spending most of the year in Portugal. International policies typically cost €800–€1,500/year for a healthy adult under 45 and offer flexibility if you travel frequently. Portuguese private policies are often better value if Porto is your primary base. D8 visa holders should confirm their policy meets the minimum coverage requirements for visa renewal.
Is flood insurance included in standard home insurance in Porto?
Not automatically. Standard Portuguese home insurance policies often cover burst pipe damage under water damage clauses, but coverage for inundação (flooding from external sources, rising rivers, heavy rainfall overflow) is frequently either excluded or requires a specific rider. If you live near the Douro waterfront, in a basement flat, or in any low-lying part of Porto or Gaia, you need to ask your broker explicitly whether external flood damage is covered. Don't assume. Claims for flood damage on policies that exclude it are one of the most common disputes in Porto's insurance market.
Can I use my European Health Insurance Card (EHIC) or Global Health Insurance Card (GHIC) instead of private health insurance in Porto?
If you're a UK citizen, your GHIC covers emergency and medically necessary treatment at Portuguese public hospitals. For EU citizens, the EHIC does the same. But these cards cover emergency access to public healthcare only, not GP appointments, specialist referrals, dental care, elective procedures, or private facilities. They don't replace private health insurance for anyone planning to live in Porto long-term. UK citizens applying for the D7 or D8 visa are also typically required to show private health insurance as part of the application, so the GHIC alone won't satisfy visa requirements.
Do I need professional liability insurance as a freelancer in Porto?
If you're providing professional services, development, design, consulting, marketing, architecture, or any other knowledge-based work, professional liability insurance is strongly advisable even if it's not always legally mandatory. For regulated professions (architects, engineers, lawyers, accountants), it's typically required by the relevant Ordem professional body. For other freelancers, the practical risk is significant: a claim from a client alleging financial loss from your work could easily exceed €50,000, which is beyond what most individuals could absorb without insurance. Porto's growing startup and tech ecosystem means freelancers