Insurance in Cascais, Complete Expat Guide 2026
Why Insurance in Cascais Is Different for Expats
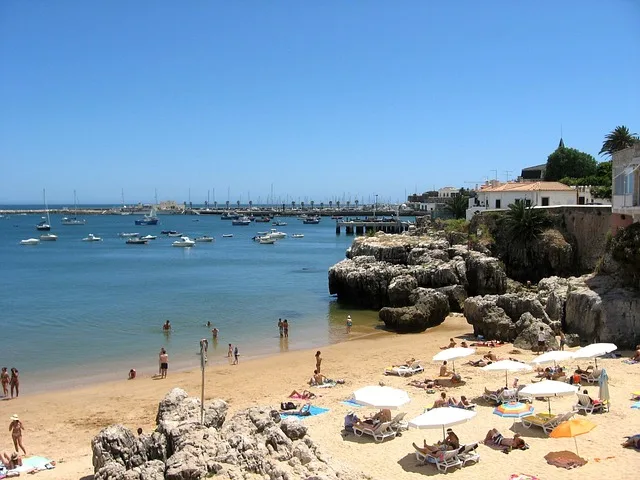
Cascais isn't just another Portuguese town. It's one of the most internationally dense municipalities in the country, with a resident expat population estimated at well over 15,000 people, Britons, Americans, Brazilians, French, Irish, and a growing wave of South Africans and Australians. That concentration of international residents has shaped the local insurance market in ways that actually work in your favour.
Brokers here are used to dealing with overseas credit histories, foreign-registered vehicles, non-habitual resident (NHR) tax situations, and clients who need policies explained in English rather than legalese. That's genuinely different from, say, trying to arrange insurance in a rural Alentejo town where every document arrives in dense Portuguese and the broker has never met a foreign client before.
But Cascais also comes with its own specific risk profile that you need to factor into your coverage decisions:
- Coastal microclimate: Salt air accelerates corrosion on vehicles and buildings faster than inland locations. It's worth checking your home and car policies cover salt-damage-related deterioration properly.
- Property values: Housing in Cascais is among the most expensive in Portugal outside central Lisbon, average purchase prices run €4,500–€7,000/m² in desirable areas like Cascais town centre, Birre, and Quinta da Marinha. That means underinsuring your property is a genuine financial risk.
- Traffic density and road complexity: The EN6 coastal road from Lisbon to Cascais is one of Portugal's busiest commuter routes and sees a high frequency of minor collisions, particularly in summer when tourist traffic multiplies. Your car insurance risk rating reflects this.
- Wildfire proximity: While Cascais itself is coastal, the Sintra-Cascais Natural Park immediately to the north has experienced significant wildfire activity in recent years. Properties in areas bordering the park, parts of São Domingos de Rana, Alcabideche, and Tires, should specifically check that their home insurance includes incêndio florestal (forest fire) cover.
- Flooding: Low-lying areas around the Ribeira de Cascais and parts of Monte Estoril experience periodic surface flooding during heavy winter rain. If you're renting or buying near these zones, flood cover (risco de inundação) is non-negotiable.
All insurance sold in Portugal is regulated by the ASF, Autoridade de Supervisão de Seguros e Fundos de Pensões. Only professionals licensed by the ASF can legally sell you an insurance contract. You can verify any broker or insurer's registration at asf.com.pt before you sign anything.
Car Insurance in Cascais, What You'll Pay and What You Need
Third-party liability insurance (seguro de responsabilidade civil automóvel) is legally mandatory for every vehicle on Portuguese roads. No exceptions, no grace periods. If you're driving in Cascais, and most residents do, because while the train line to Lisbon is excellent, getting around the wider municipality without a car is genuinely difficult, you need this as a baseline minimum.
What most Cascais expats actually buy is comprehensive cover (seguro contra todos os riscos), and for good reason. The EN6 and the IC15 corridor are heavily used, parking in Cascais town centre is tight and scrapes happen, and the value of cars here tends to be higher than the national average. Comprehensive cover in the Cascais area typically runs:
- Third-party only: €300–€600/year for a standard family car
- Third-party, fire and theft: €450–€750/year
- Comprehensive (all risks): €700–€1,400/year
Your premium will be influenced by where in Cascais you live. Postcodes in the 2750 and 2765 areas (Cascais town, Estoril, Monte Estoril) carry higher risk ratings than addresses further inland toward São Domingos de Rana or Alcabideche, simply because of traffic density and theft statistics along the coastal strip.
Practical tips specific to Cascais drivers:
- Summer surcharges: Some insurers apply seasonal risk adjustments for the Cascais coastal corridor between June and September. Ask your broker about this before you sign.
- Parking location matters: If you have a private garage or underground parking, say so, it can reduce your premium by 10–15% compared to street parking.
- Foreign no-claims history: Portuguese insurers will accept proof of no-claims bonus (NCB) from UK, French, German and most EU insurers. Bring documentation. American and South African NCB is trickier but some specialist brokers can work with it.
- Motorcycle use is common: Many expats use scooters or motorcycles to navigate Cascais town. If that's you, check our guide to motorcycle insurance Portugal, it's a separate policy from your car cover and premiums vary significantly by engine size.
For a full breakdown of Portuguese car insurance requirements, excess structures, and how to transfer foreign policies, see our dedicated guide on car insurance Portugal.
Health Insurance in Cascais, Private Cover That Actually Works Here
This is where most Cascais expats spend the most time researching, and rightly so. Portugal has a public health system (Serviço Nacional de Saúde, SNS), and once you're registered at your local health centre (centro de saúde) in Cascais, you're entitled to use it. The centro de saúde serving central Cascais is on Rua do Mercado, but be prepared for waiting times for specialist appointments that can run to months.
The vast majority of established expats in Cascais hold private health insurance alongside their SNS entitlement. Here's why that combination makes sense:
- The Hospital de Cascais (Hospital Dr. José de Almeida) is a privately managed PPP hospital and accepts patients with private insurance with minimal waiting. It's genuinely good and well-regarded locally.
- CUF Cascais clinic on Avenida Marginal is a popular choice among expats for specialists and diagnostics, English-speaking staff, efficient appointments.
- Dental care is almost never included in basic SNS access, which is why many expats add standalone dental insurance Portugal, typically €20–€60/month depending on coverage level.
Private health insurance costs in the Cascais area for expats in 2026:
- Under 40, basic plan: €600–€900/year
- 40–55, mid-range plan with specialists: €900–€1,400/year
- 55–65, comprehensive plan: €1,400–€2,200/year
- 65+: €2,000–€3,500+/year depending on pre-existing conditions
If you're a digital nomad or remote worker on a D8 visa, private health insurance is a mandatory condition of your visa. The SNS alone won't satisfy the requirement. For detailed guidance on what visa-compliant health plans look like, our health insurance Portugal expats guide covers the requirements by visa category.
One thing that catches people out in Cascais specifically: the town is popular with retirees aged 65+ who moved here believing their European Health Insurance Card (EHIC or GHIC for UK nationals) provides full cover. It doesn't, it provides basic access to the SNS on the same terms as Portuguese residents, not private care. If you're a British retiree who moved here post-Brexit on a residency visa, private health insurance is essential.
Home and Property Insurance in Cascais, Rental vs Ownership
Whether you rent or own in Cascais, you need property insurance. The specifics differ significantly between the two situations.
If You Own Property in Cascais
If you have a mortgage, buildings insurance (seguro de incêndio, fire and multi-risk) is mandatory under Portuguese banking law. Your bank will typically require it as a condition of the mortgage and may offer their own product. You are legally entitled to choose your own insurer rather than the bank's tied product, and doing so often saves €100–€300/year.
Given Cascais property values, getting the sum insured right is critical. A 120m² apartment in Cascais town needs to be insured for its rebuild cost, typically €1,200–€1,800/m² for construction in this area, not its market value. These are very different numbers and underinsurance is a common, expensive mistake.
Buildings insurance (multi-risk) in Cascais typically costs:
- Apartment, €300,000 rebuild value: €300–€600/year
- Villa with garden, €600,000 rebuild value: €700–€1,400/year
Specific risks to cover in Cascais home policies:
- Forest fire (incêndio florestal): Essential for any property bordering the Sintra-Cascais Natural Park, Alcabideche, parts of Birre, and areas above the A5.
- Flooding (inundação): Important for lower-lying properties near the Cascais town centre waterfront and Monte Estoril's older streets.
- Salt and coastal corrosion: Not always standard, ask your broker explicitly about this, especially for roofs, external metalwork, and shutters.
- Theft and break-in (furto e roubo): Cascais town centre and the Estoril strip see higher rates of opportunistic theft than inland areas. Make sure your contents limit is realistic.
For comprehensive guidance on Portuguese property insurance structures, see our home insurance Portugal guide.
If You Rent in Cascais
Your landlord's buildings insurance covers the structure. It does not cover your belongings. A renters' contents insurance (seguro de recheio) is highly recommended and remarkably affordable, typically €80–€200/year for a furnished apartment with €20,000–€40,000 of contents cover. Given the quality of furniture many Cascais expats bring or buy, that coverage limit is worth reviewing carefully.
Life Insurance for Expats in Cascais
Life insurance (seguro de vida) in Portugal comes in two main forms: mortgage-linked cover (vida crédito), which your bank will push hard, and standalone term or whole-of-life policies you arrange independently.
If you've bought property in Cascais with a mortgage, the bank will require a life policy. Again, you're not obliged to buy it from them. Independent term life insurance for a healthy non-smoker in their 40s in Cascais typically costs:
- €200,000 cover, 20-year term, age 40: €20–€40/month
- €400,000 cover, 20-year term, age 45: €45–€80/month
- €200,000 cover, 15-year term, age 55: €60–€110/month
Expats in Cascais often overlook the importance of structuring life insurance correctly for cross-border family situations, if your beneficiaries live in the UK, Ireland, or France, there are tax and inheritance implications worth discussing with both your broker and a tax adviser. Our life insurance Portugal expat guide covers the key structures used by expats here.
British retirees specifically: if you moved to Cascais and your pension income stops at death (leaving a spouse with reduced income), a relatively modest life policy can bridge that gap affordably while you're in reasonable health.
Professional and Freelance Insurance in Cascais
Cascais has a thriving community of self-employed expats, remote workers, and freelancers, architects, consultants, IT specialists, coaches, therapists, and a growing number of people running location-independent businesses from the Linha de Cascais. If you earn income in Portugal, even as a recibos verdes (freelance invoice) worker, there are insurance considerations you can't ignore.
Professional Liability (Responsabilidade Civil Profissional)
If you provide professional advice, services, or expertise to clients, and this includes remote work for non-Portuguese clients, professional liability insurance protects you if a client claims your work caused them financial loss. Some professions in Portugal require it by law (architects, engineers, lawyers, financial advisers). Others need it to win contracts or satisfy client requirements.
RC Pro premiums for Cascais-based freelancers typically run €200–€800/year depending on your profession, revenue, and coverage limit. Our professional liability insurance Portugal guide explains the structures most relevant to expat freelancers.
Digital Nomad and D8 Visa Holders
Cascais is genuinely popular with digital nomads, the Linha train to Lisbon, the coworking spaces around Cascais town, the lifestyle, and the relative affordability compared to Lisbon's centre all attract remote workers. If you're on a D8 Digital Nomad Visa, you must maintain valid health insurance. Many D8 holders in Cascais use international health insurance plans designed for nomads rather than standard Portuguese domestic plans, the difference matters if you travel frequently for work.
If you work remotely for a non-Portuguese company, also check whether you need travel insurance Portugal as a separate product for business travel, since your standard health insurance may not cover medical emergencies abroad.
The Expat Community in Cascais, What Locals Know
Understanding Cascais's expat community matters for insurance because word-of-mouth is genuinely valuable here, but it can also be misleading if the advice comes from someone whose situation is different from yours.
The community breaks down roughly like this:
- British retirees: The largest historic expat group, many settled pre-Brexit with EU residency rights. Concentrated in Cascais town, Estoril, Monte Estoril, and the quieter streets above the Marginal. Insurance needs skew toward health, home, and life products.
- American and Canadian families: Often here on D7 or golden visa-derived residency. Cascais International School and St. Julian's School proximity drives family location choices. Home insurance with high contents values and health insurance with English-language support are priorities.
- Brazilian and Lusophone expats: A large and growing community, often in the Cascais-Tires and São Domingos de Rana areas where property is more affordable. Tend to be younger and working, so car and health insurance are key.
- French and Belgian retirees: Found particularly in Estoril and quieter Cascais neighbourhoods. Many arrive with existing French mutuelle or Belgian supplementary health policies that may or may not be valid for long-term Portuguese residency, worth checking carefully.
One thing experienced Cascais expats consistently flag: don't rely solely on insurance advice from expat Facebook groups. You'll get fifteen different opinions, most of them based on individual circumstances, and some of them outdated. The Portuguese insurance market changes regularly in terms of what's available, what visa categories require, and what ASF-compliant products look like. What worked for someone who arrived in 2019 may not be right for your 2026 situation.
Local expat social groups, the British-Portuguese Society, various WhatsApp networks, and the Cascais Expat Community Facebook group, are excellent for finding recommended brokers and getting personal experiences. They're less reliable for specific coverage advice.
How to Get Insured in Cascais: Step-by-Step
Here's the practical sequence most expats in Cascais follow when they arrive and need to sort their insurance properly.
- Get your NIF first. Your Número de Identificação Fiscal is essential for virtually any financial transaction in Portugal, including taking out insurance policies. You can get it at any Finanças office, there's one in Cascais on Rua Sebastião Magalhães Lima. Takes 15–30 minutes if you have your passport and proof of address.
- Register with the SNS. Even if you're getting private health insurance, register at your local centro de saúde. It costs nothing, gives you a SNS number, and provides a backup layer of care you may need at some point.
- Sort car insurance before you drive. If you're importing a vehicle from the UK or another country, you need Portuguese insurance before you re-register the car. A Portuguese insurer will accept a foreign policy temporarily in some cases, but don't rely on this, get Portuguese cover sorted promptly.
- Identify your visa category and its insurance requirements. D7, D8, D2, NHR status, each has slightly different implications for what you need to hold. An ASF-licensed broker who works with expats will know this.
- Work with a broker, not direct-to-insurer. The Portuguese insurance market has dozens of providers. A qualified broker compares across the market, handles paperwork in English if needed, and knows which insurers are reliable for expat claims. This service typically costs you nothing, brokers are paid by commission from insurers.
- Don't bundle blindly. Banks in Portugal frequently offer bundled insurance packages with mortgages. You may be better served by separate, individually chosen policies for each risk. A broker can tell you within minutes whether the bank's package is competitive.
- Review annually. Insurance needs change. If you got your first policies when you arrived in Cascais, your life may look quite different two years later, different property value, different family situation, different income. A 30-minute annual review with your broker is worth doing.
Ready to Get the Right Cover for Cascais?
We'll connect you with an ASF-licensed broker who specialises in expat insurance on the Linha de Cascais. They speak English, know the local market, and will compare products across multiple insurers to find the right fit for your situation.
Get Your Free Quote, Takes 2 MinutesFrequently Asked Questions, Insurance for Expats in Cascais
Do I need different insurance in Cascais compared to Lisbon?
The legal requirements are the same across Portugal, but the risk profile is different. Cascais has higher property values (meaning underinsurance is more costly), specific coastal and wildfire risks the Lisbon city centre doesn't share, and a different traffic pattern on the EN6 and IC15 that affects car insurance premiums. You'll also find the Cascais broker market is well-developed for English-speaking expats, which makes the process smoother than in many other areas.
How does living in Cascais affect my car insurance premium?
Your postcode is one of the factors Portuguese insurers use to price car insurance. The 2750 and 2765 postal districts (Cascais town, Estoril, Monte Estoril) carry higher risk ratings than inland areas, reflecting traffic density and theft frequency along the coastal strip. Living in Cascabide or São Domingos de Rana may attract a slightly lower premium than living in Cascais town itself. Comprehensive cover in Cascais typically costs €700–€1,400/year for a standard family car, compared to €500–€1,100 in quieter inland municipalities.
What health insurance do digital nomads use in Cascais?
D8 Digital Nomad Visa holders in Cascais generally use one of two approaches: a standard Portuguese private health insurance plan from a major domestic insurer (which gives full access to Cascais's private clinics like CUF and Hospital de Cascais), or an international health insurance plan designed for location-independent workers that covers them both in Portugal and when travelling abroad for work. The right choice depends on how much you travel and whether you need repatriation cover. Both approaches satisfy the D8 visa's mandatory health insurance requirement, provided the policy meets the minimum coverage thresholds.
My property is near the Sintra-Cascais Natural Park, what specific cover do I need?
Properties in areas bordering the park, particularly parts of Alcabideche, Birre, and the hillside areas above the A5, face meaningful wildfire risk. Your home insurance policy must explicitly include incêndio florestal (forest fire) cover. Many standard multi-risk policies include fire cover for the building itself but not for landscaping, outbuildings, or vehicles left outside. Read your policy terms carefully, or ask your broker to confirm in writing what wildfire scenarios are and aren't covered. Properties in these areas may also benefit from cover for smoke damage even when fire doesn't directly affect the structure.
Can I use my existing UK, French or other European health insurance in Cascais?
Short answer: probably not for long-term residency. EU and UK travel health insurance products (including the EHIC/GHIC) are designed for temporary stays, not residency. Once you're a legal resident in Portugal, you're generally expected to access healthcare through the SNS or Portuguese private health insurance. Some expats maintain international health plans originally taken out before moving, and these can sometimes be extended to cover Portuguese residency, but the terms vary enormously by insurer. Have this checked by an ASF-licensed broker or a specialist in expat health plans before you assume you're covered.
Is renters' insurance worth getting in Cascais if I'm only here for a year or two?
Yes, and it's one of the cheapest policies you'll ever buy. Contents insurance for a furnished Cascais apartment typically runs €80–€200/year and covers theft, fire, water damage, and accidental damage to your belongings. Given that furnished rentals in Cascais often include high-value furnishings and that theft from residential properties along the coastal strip does occur, particularly in ground-floor or easily accessible flats, the €150 annual premium is genuinely worth it. It also typically includes personal liability cover, which protects you if you accidentally cause damage to the property or injure someone in it.